Malta’s New Gaming Tax, Explained
23 October, 2026
by Julie Courte
Malta’s gaming tax may have tripled on paper, but for most operators, that headline tells only part of the story.
Since 1 October 2026, the Malta gaming tax has moved from a flat 5% to a tiered structure: 15% for Type 1 games and 10% for Types 2, 3 and 4.
The “5% to 15%” figure has spread quickly across LinkedIn, and it is accurate. What it leaves out is the detail that matters most: the tax applies only to revenue from players based in Malta. For an operator whose players are mostly in other markets, that is a very small slice of the business.
Here is what changed, what stayed the same, and what we recommend you check before the first return under the new regime falls due.
The new Malta gaming tax rates
The changes come from Legal Notice 84 of 2026, which amends Malta’s Gaming Tax Regulations. The government published it on 1 April, and it took effect on 1 October. Rates now depend on the type of game you offer and apply to aggregate gaming revenue.
| Game type | Before 1 October 2026 | From 1 October 2026 |
|---|---|---|
| Type 1 (casino-type games, live casino, lotteries) | 5% | 15% |
| Type 2 (fixed-odds betting) | 5% | 10% |
| Type 3 (commission-based games such as P2P poker, bingo and betting exchanges) | 5% | 10% |
| Type 4 (controlled skill games) | 5% | 10% |
Land-based activity in controlled gaming premises, as well as junkets and junket events, now carries a 5% rate. At the same time, the device-based levy disappears, while the studio broadcasting levy rises from €500 to a fixed €3,000 a year.
According to the joint announcement by the Malta Gaming Authority (MGA) and the Malta Tax and Customs Administration (MTCA), the reform followed extensive engagement with the industry and delivers on a 2026 Budget commitment to keep the sector sustainable and competitive.
Who pays the Malta gaming tax? Only Malta-based players count
This is where the headline and the reality part ways. The tax covers gaming services provided from Malta or to people in Malta. For remote gaming, a player falls within scope when they are established in Malta, have a permanent address there, or usually reside there. The MGA has also stated that the amended rates apply exclusively to gaming services provided within Malta.
Revenue from players who are not resident or established in Malta sits outside the Malta gaming tax altogether. In other words, the perimeter is exactly the same as under the old 5% regime. Only the rate inside it has changed.
What does this look like in numbers?
Take an illustrative MGA-licensed casino operator with €20 million in annual gaming revenue, of which 1% (€200,000) comes from Malta-based players. Under the old re-gime, the gaming tax on that revenue was €10,000. At the new 15% Type 1 rate, it is €30,000.
The rate has tripled, yet the additional €20,000 equals just 0.1% of the operator’s total revenue. Your own figures will differ, so the first step is to know your Malta-player share.
What stays the same
The MGA compliance contribution remains a separate charge, calculated on gaming revenue across all markets, and this amendment does not change its rates. Likewise, your license, your game type classifications and the monthly return cycle all stay in place.
The VAT change for Malta gaming operators
While the gaming tax grabbed the headlines, Legal Notice 86 of 2026 changed the VAT treatment of gambling on the same day. For many operators, this is the bigger change, and it is largely good news.
Most gaming becomes taxable for VAT
Until now, most gaming supplies were exempt from VAT without credit, so operators could not recover the VAT they paid on their own costs. From 1 October, that exemption is much narrower. Online casino, live casino, sports betting, poker, RNG games and most B2B gaming supplies now generally count as taxable supplies. Only low-risk games, occasional junket events and in-venue betting at sporting events remain exempt.
Taxable does not automatically mean you charge VAT to your players at the standard rate. It means the supply sits inside the VAT system, and the rate, any exemption and your recovery rights still need checking.
Input VAT you can now recover
This is where operators stand to gain. Taxable supplies bring a right to recover input VAT on eligible costs, such as technology and IT infrastructure, marketing and advertising, and professional and outsourced services.
Consider an operator that spends €100,000 on eligible costs plus €18,000 in Maltese VAT. Under the old rules, that €18,000 was a sunk cost. Under the new rules, it may be fully recoverable. Operators whose activities become fully taxable may also no longer need partial attribution, the calculation used to split recoverable and non-recoverable VAT. That means simpler returns and less VAT lost.
Sports betting now follows the player
Online sports betting is now treated as an electronically supplied service, which brings Malta in line with the EU member states. In practice, the VAT treatment follows where the player is established, so the rules of the player’s country, including any local exemption, apply. For operators, that means a clearer, more predictable position that matches the rest of the EU.
Key dates for your next returns
September 2026 returns still follow the old regime. You submit them through the MGA Portal by 20 October 2026.
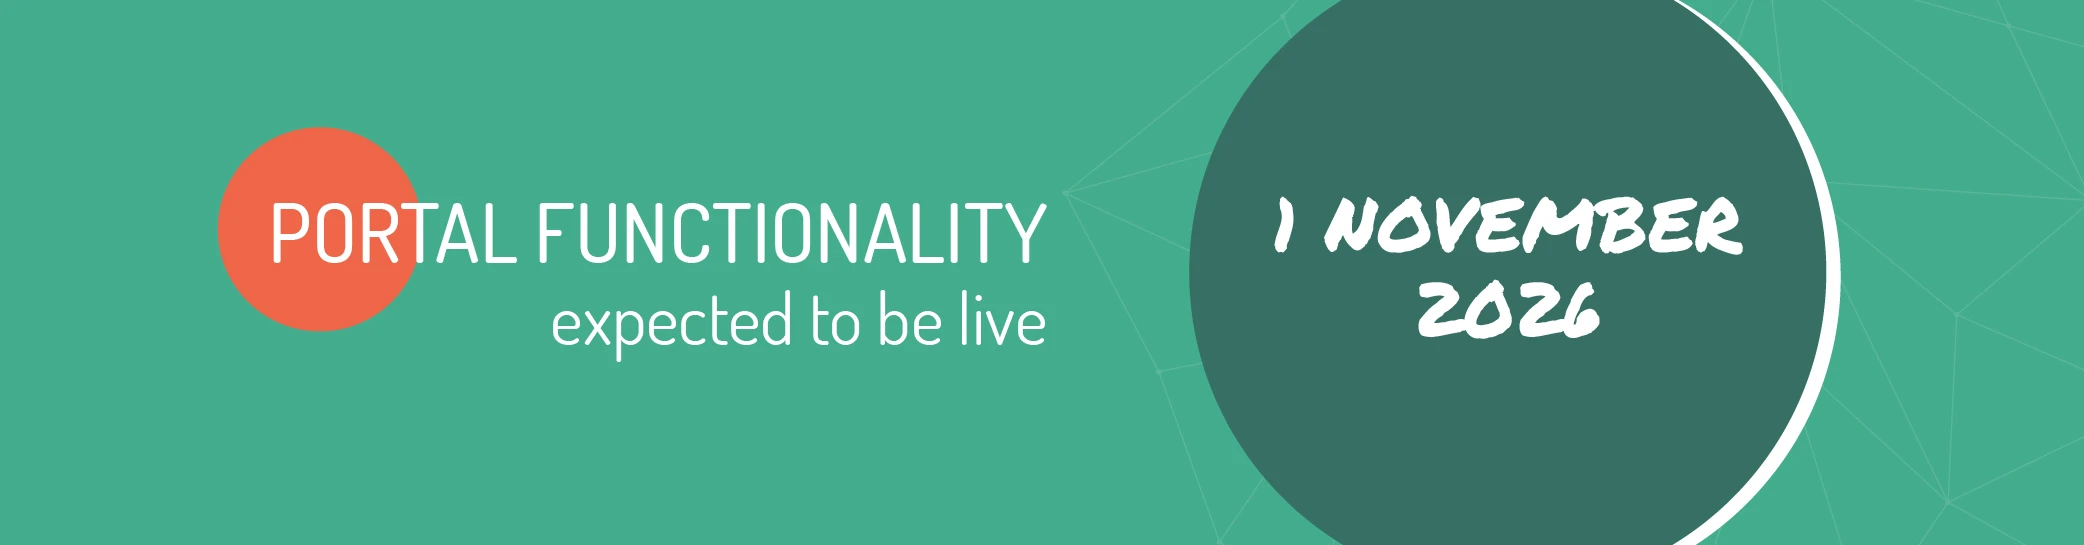
The MGA expects Portal functionality for the new framework to be live by 1 November 2026. After that, returns of October 2026 onwards become the first filed at the new rates.
What we recommend you do now
Before you file your next return, it is worth checking three things: your Malta-player revenue by game type, your VAT position and your cash flow forecast.
Our Sliema team knows both the rules and how things get done in Malta. We have supported MGA licensees since 2014, from new license applications to post-acquisition restructuring, pairing Dutch clarity with Maltese colleagues who know the local land-scape. If you would like help with any of this, talk to us.